Quick Answer
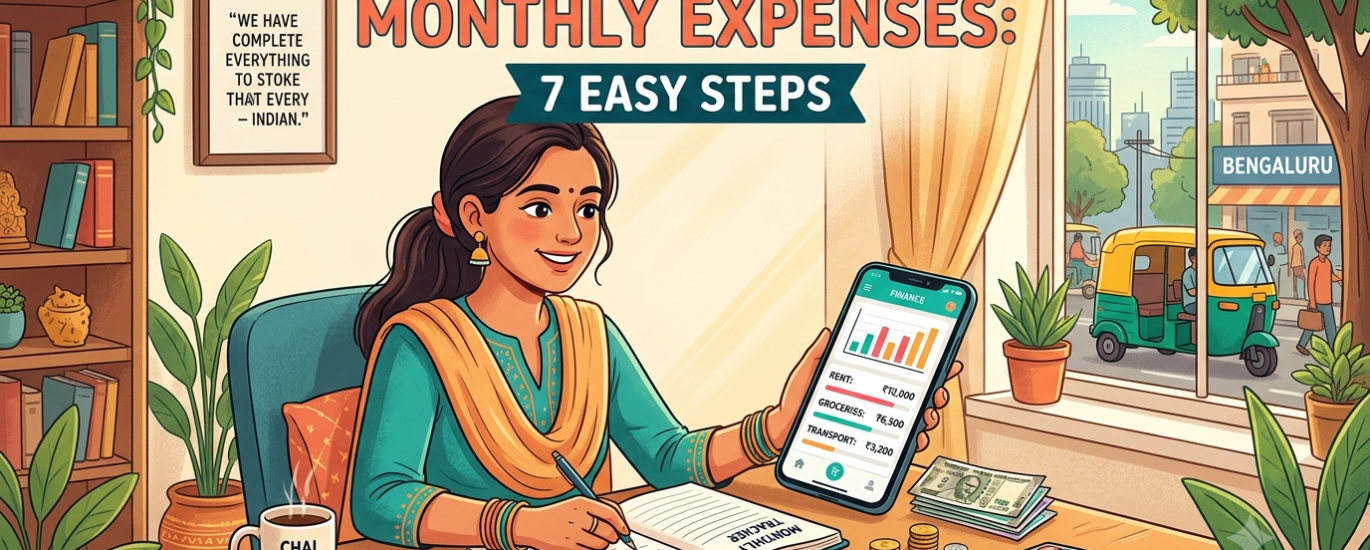
Tracking monthly expenses means recording the money you spend, categorising your purchases, and comparing actual spending with your budget. It helps you identify unnecessary expenses, control overspending, plan savings and work toward financial goals.
You can track expenses using a notebook, spreadsheet, budgeting app or bank statements. The most effective method is one you can maintain consistently.
Key Facts
- Record expenses daily or as soon as practical.
- Separate essential expenses from lifestyle spending.
- Include cash, UPI, debit card, credit card and automatic payments.
- Compare actual spending against your monthly budget.
- Review recurring subscriptions and small frequent purchases.
- Set a monthly savings target before spending the remaining income.
SEBI recommends creating a budget, tracking spending, prioritising essential expenses and allocating money toward savings and investments. (SEBI Investor Education)
What Is Monthly Expense Tracking?
Monthly expense tracking is the process of recording and reviewing all your spending over a month. It helps you understand where your income goes and whether your spending matches your financial priorities.
For example, someone earning ₹40,000 might believe that most of their income goes toward rent and groceries. Recording every transaction may reveal that frequent food deliveries, shopping and subscriptions also account for a substantial amount.
Expense tracking works best when combined with a monthly budget planner for India. A budget sets your spending plan, while expense tracking shows whether you are following it.
Why Should You Track Your Expenses?
Tracking expenses gives you a clearer picture of your financial situation and helps you make informed decisions about spending.
| Benefit | How It Helps |
|---|---|
| Better spending control | Identifies purchases that can be reduced |
| Higher savings potential | Reveals money that could be redirected to savings |
| Debt management | Helps monitor credit card bills and loan payments |
| Emergency preparation | Makes it easier to plan regular contributions |
| Financial goal planning | Helps allocate money toward specific goals |
| Household management | Makes shared expenses easier to review |
The Reserve Bank of India explains that budgeting can help people compare planned spending with actual expenditure and identify areas where they have spent more or less than expected. (RBI Financial Awareness Messages)
How to Track Monthly Expenses in 7 Steps
Step 1: Calculate Your Monthly Income
Start with the income available to you after salary deductions. Include other reliable income sources, such as freelance earnings or rental income, if applicable.
For irregular income, use a conservative estimate rather than assuming that every month will be equally profitable.
| Income Source | Example Amount |
|---|---|
| Monthly take home salary | ₹40,000 |
| Freelance income | ₹3,000 |
| Total monthly income | ₹43,000 |
Use the amount you can reasonably expect to receive, not an uncertain bonus or potential future income.
Step 2: Record Every Expense
Record each transaction, including small purchases that are easy to forget. Daily recording is usually more reliable than trying to reconstruct an entire month from memory.
Include expenses paid through:
- UPI transactions
- Cash
- Debit and credit cards
- Bank transfers
- Automatic bill payments
- Online shopping platforms
- Subscriptions and memberships
Do not count a credit card purchase twice. Record the original purchase as the expense and treat the later credit card bill payment as settlement of that liability.
Step 3: Categorise Your Spending
Group transactions into categories so that you can see which areas consume most of your income.
| Category | Examples |
|---|---|
| Housing | Rent, maintenance, home loan |
| Food | Groceries, restaurants, food delivery |
| Utilities | Electricity, water, mobile, internet |
| Transport | Fuel, public transport, vehicle maintenance |
| Healthcare | Medicines, consultations, medical supplies |
| Debt | Loan instalments, interest, credit card charges |
| Lifestyle | Shopping, entertainment, subscriptions |
| Savings | Emergency fund and planned savings |
Keep essential spending separate from optional purchases. SEBI explains that distinguishing needs from wants can help people prioritise expenses and increase their savings. (SEBI: Understanding Needs and Wants)
Step 4: Choose an Expense Tracking Method
The best expense tracking tool is one that fits your routine and makes regular reviews easy.
| Method | Best For | Main Limitation |
|---|---|---|
| Notebook | People who prefer writing expenses manually | Requires consistent manual entry |
| Spreadsheet | People who want detailed calculations | Needs regular updating |
| Budgeting app | People who prefer digital records | Features and data handling vary |
| Bank statements | Reviewing recorded banking transactions | May miss cash spending |
| UPI history | Reviewing digital payments | Does not show every expense source |
You do not need a paid app to get started. A basic spreadsheet with date, description, category and amount is enough for many households.
Step 5: Compare Actual Spending With Your Budget
At the end of each week, compare your recorded expenses with your spending plan. This helps you identify problems before the month ends.
For example, if you planned ₹4,000 for dining out but spent ₹3,500 in the first two weeks, you have used most of your allocation before the month is halfway through.
You can then reduce further discretionary spending or adjust your plan if the expense was necessary.
Step 6: Identify Expenses You Can Reduce
Review recurring charges and frequent purchases before cutting essential household spending.
Look for:
- Unused subscriptions
- Repeated food delivery orders
- Impulse purchases
- Unnecessary convenience fees
- Unplanned online shopping
- Avoidable late payment charges
- Services you no longer use
Small expenses can add up over time, but do not assume every small purchase is wasteful. Evaluate spending according to your needs, priorities and budget.
Step 7: Review and Update Your Plan Monthly
A monthly review helps you understand whether your spending habits are improving. Compare this month’s expenses with the previous month and decide what needs to change.
Review these five questions:
- Did I stay within my planned budget?
- Which category exceeded its limit?
- Were there any unexpected expenses?
- Did I meet my savings target?
- What adjustment should I make next month?
The RBI recommends keeping budgeting simple, reviewing it monthly and planning for unexpected expenses that can disrupt a budget. (RBI Financial Education Guide)
Monthly Expense Example for a ₹40,000 Salary
Consider an employee earning ₹40,000 per month after deductions. The following example shows how expense tracking can reveal opportunities to improve savings.
| Expense Category | Planned Budget | Actual Spending |
|---|---|---|
| Rent and maintenance | ₹10,000 | ₹10,000 |
| Groceries | ₹5,000 | ₹5,500 |
| Utilities and mobile | ₹2,000 | ₹1,800 |
| Transport | ₹3,000 | ₹3,500 |
| Healthcare | ₹1,000 | ₹800 |
| Dining and entertainment | ₹4,000 | ₹5,000 |
| Shopping and subscriptions | ₹3,000 | ₹4,000 |
| Other expenses | ₹2,000 | ₹2,000 |
| Total expenses | ₹30,000 | ₹32,600 |
| Remaining income | ₹10,000 | ₹7,400 |
In this example, actual spending exceeds the plan by ₹2,600. The person can investigate the extra spending on groceries, transport, dining and shopping before deciding where adjustments are realistic.
The remaining ₹7,400 is a calculation based on the example, not a recommendation that this amount is sufficient for every person’s savings needs.
How to Track Expenses Using a Spreadsheet
A simple spreadsheet can provide a useful record without requiring specialised software.
Use these columns:
| Date | Description | Category | Payment Method | Amount |
|---|---|---|---|---|
| 1 October | Grocery shopping | Food | UPI | ₹1,200 |
| 2 October | Fuel | Transport | Card | ₹700 |
| 3 October | Mobile bill | Utilities | UPI | ₹500 |
| 4 October | Restaurant | Dining | UPI | ₹650 |
At the end of the month, total the Amount column and calculate category totals. Compare these totals with your planned budget.
For a simple spreadsheet, you can use a SUM formula to calculate total expenses. A SUMIF formula can total transactions belonging to a particular category.
How Does Expense Tracking Support the 50/30/20 Budget Rule?
Expense tracking helps you check whether your actual spending follows your intended budget allocation.
The 50/30/20 framework suggests allocating 50% of income to needs, 30% to wants and 20% to savings or debt repayment. These percentages are guidelines, not official Indian regulatory requirements.
For a ₹40,000 monthly take home income, the suggested allocations would be:
| Category | Percentage | Amount |
|---|---|---|
| Needs | 50% | ₹20,000 |
| Wants | 30% | ₹12,000 |
| Savings and debt repayment | 20% | ₹8,000 |
If your essential expenses already exceed ₹20,000, adjust the allocation to reflect your circumstances. You can read our detailed guide to the 50/30/20 budget rule in India.
Common Expense Tracking Mistakes
Avoid these common mistakes when setting up your tracking system.
- Forgetting cash purchases: Record small transactions as well as large payments.
- Mixing needs and wants: Separate essential costs from optional lifestyle spending.
- Ignoring annual expenses: Plan for insurance renewals, vehicle servicing and other periodic payments.
- Counting payments twice: Do not record both a credit card purchase and the later bill payment as separate expenses.
- Tracking without reviewing: Use your records to make practical changes.
- Setting unrealistic limits: Create a budget that reflects actual living costs and financial obligations.
What You Need to Start Tracking Expenses
You do not need special eligibility or financial expertise to track personal spending. You only need a reliable record of income, expenses and payment dates.
| Requirement | What to Prepare |
|---|---|
| Income record | Salary slip or income statement |
| Expense records | Bank statements, UPI history and cash notes |
| Categories | Housing, food, transport, debt and lifestyle |
| Tracking tool | Notebook, spreadsheet or suitable app |
| Review schedule | A few minutes daily and a monthly review |
| Financial target | A realistic spending or savings goal |
Protect your financial information when using digital tools. Avoid sharing banking passwords, card PINs or one time passwords with budgeting services or other people.
Expert View
Effective expense tracking depends more on consistency than on the tool you choose. A simple system that records transactions accurately and is reviewed every month can be more useful than a sophisticated app that you rarely update.
SEBI’s financial education guidance recommends tracking spending, prioritising essential expenses, maintaining emergency savings and allocating money toward financial goals. (SEBI Investor Education)
Frequently Asked Questions
1. What is the easiest way to track monthly expenses?
A notebook or spreadsheet is a simple starting point. Record each expense, assign a category and compare the monthly total with your budget.
2. Can I track expenses using UPI history?
Yes. UPI transaction history can help you review digital payments, but you should also record cash purchases, card transactions and automatic payments.
3. How often should I record expenses?
Daily recording is a useful approach because it reduces the chance of forgetting purchases. You can review category totals weekly and assess your overall budget monthly.
4. How can I reduce monthly expenses?
Identify the categories that exceed your budget, review subscriptions and reduce unnecessary purchases. Avoid cutting essential healthcare, insurance or other necessary costs without considering the consequences.
5. Should savings be counted as an expense?
For budgeting purposes, you can treat planned savings as a separate allocation made before discretionary spending. In accounting terms, savings are not the same as a consumption expense.
6. Which expense tracking app is best in India?
The best app depends on your needs, preferred features, cost and privacy requirements. A spreadsheet may be sufficient if you want a simple record without giving another service access to your financial data.
7. How do I track expenses when my income changes every month?
Use a conservative estimate of income and prioritise essential expenses first. When you receive additional income, allocate it according to your savings goals, outstanding debt and other financial priorities.
8. Does tracking expenses help build savings?
Tracking can reveal spending that may be reduced and help you set a more realistic savings target. The amount you can save will depend on your income, necessary expenses and financial obligations.
Sources
- SEBI: Management of Income and Expenses
- SEBI: Understanding Needs, Wants and Desires
- SEBI: Financial Goals and Budgeting
- RBI: Financial Awareness Messages
- RBI: Financial Education Guide
Related Fundbone Guides
- Personal Finance in India: Complete Guide
- How to Create a Monthly Budget in India
- 50/30/20 Budget Rule in India
- Needs vs Wants: How to Control Spending
- How Much Should You Save Every Month?
- How to Build an Emergency Fund in India
Disclaimer: This article is for educational purposes only and does not constitute financial, investment, tax or legal advice. Review your own financial circumstances before making financial decisions.

3 thoughts on “How to Track Monthly Expenses in India: A Step by Step Guide”