Quick Answer
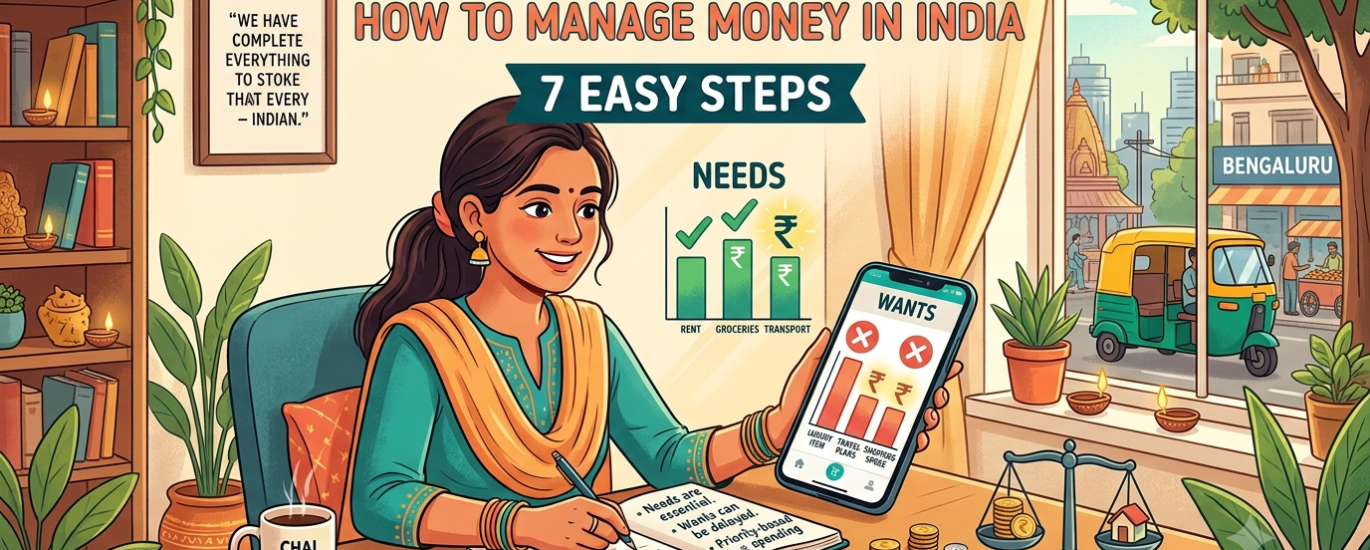
Needs are expenses required for essential living and important financial obligations, such as groceries, housing, utilities and necessary healthcare. Wants are purchases that improve comfort or lifestyle but can usually be postponed, such as luxury shopping, dining out and premium subscriptions.
Understanding the difference helps you control spending, create a realistic budget and save more consistently. The goal is not to eliminate every want, but to balance lifestyle spending with essential expenses and future financial goals.
Key Facts
- Needs support basic living, health, safety and essential responsibilities.
- Wants improve comfort, convenience or enjoyment but are usually flexible.
- The same purchase can be a need or a want depending on its purpose and cost.
- Tracking expenses helps identify spending that can be reduced.
- Savings should be included in your financial plan rather than left to chance.
- The 50/30/20 budget rule is a budgeting framework, not a mandatory government rule.
The Reserve Bank of India explains that distinguishing needs from wants is an important first step in managing money successfully. It also notes that wants can often be postponed to help achieve financial goals. (RBI financial literacy material)
What Are Needs?
Needs are expenses required to maintain your basic standard of living, health and essential responsibilities. They should generally receive priority when you prepare your monthly budget.
Examples include:
- Rent or essential housing costs
- Basic groceries
- Electricity and water
- Necessary transportation to work
- Essential medicines and healthcare
- Basic clothing
- Minimum required loan payments
- Essential insurance premiums
The cost of a need can vary between households. For example, paying for transport to reach work may be necessary, while choosing a premium vehicle when a more affordable option meets your requirements may be a lifestyle preference.
What Are Wants?
Wants are expenses that make life more comfortable or enjoyable but can usually be reduced, delayed or replaced with a less expensive alternative.
Examples include:
- Restaurant meals and food delivery
- Premium smartphones
- Designer clothing
- Entertainment subscriptions
- Expensive holidays
- Unplanned online shopping
- Upgrading a working device for a newer model
- Luxury accessories
Wants are not automatically bad financial decisions. They become a problem when discretionary spending prevents you from paying essential bills, managing debt or building savings.
Needs vs Wants: Key Differences
| Factor | Needs | Wants |
|---|---|---|
| Purpose | Supports essential living | Improves lifestyle or comfort |
| Priority | Usually high | Depends on available income |
| Flexibility | Often limited | Usually more flexible |
| Spending control | Focus on reasonable cost | Set limits and compare alternatives |
| Examples | Basic groceries, rent, essential medicines | Dining out, luxury shopping, premium gadgets |
| Financial approach | Plan and pay first | Spend within the remaining budget |
The distinction depends on the circumstances, not only the product. A mobile phone may be necessary for work, while buying the latest premium model may be optional.
Real Life Examples of Needs and Wants in India
| Purchase | Likely Category | Explanation |
|---|---|---|
| Monthly groceries | Need | Food is essential |
| Premium restaurant dinner | Want | A lower cost meal may meet the same basic need |
| Basic phone for work | Need | Communication may be essential |
| Expensive phone upgrade | Want | The upgrade may not be necessary |
| Fuel for daily commuting | Need | If required to reach work |
| Weekend leisure trip | Want | Usually flexible and postponable |
| Prescribed medicine | Need | Required healthcare should be prioritised |
| Multiple streaming subscriptions | Want | Some subscriptions can be reduced or cancelled |
| Basic work clothing | Need | May be necessary for employment |
| Designer clothing beyond requirements | Want | Often a discretionary purchase |
Use these categories as a guide rather than strict rules. Medical needs, accessibility requirements, family circumstances and employment conditions can change how an expense should be classified.
How to Separate Needs From Wants
Step 1: Ask Whether the Expense Is Necessary
Before buying something, ask whether it supports basic living, health, safety, work or an important financial obligation.
If the expense is necessary, identify the most reasonable option that meets the requirement.
Step 2: Check Whether You Can Postpone It
If you can delay the purchase without affecting your health, safety or essential responsibilities, it may be a want.
For example, replacing a broken refrigerator may be necessary, while upgrading a working refrigerator for additional features may be optional.
Step 3: Compare the Cost With Your Budget
An expense can be justified but still too expensive for your current financial situation. Compare the cost with your income, existing commitments and savings target.
Step 4: Look for a Practical Alternative
You may be able to reduce costs without removing the underlying benefit. Options include cooking at home more often, reviewing subscriptions, choosing a suitable lower cost product or delaying a non urgent purchase.
Step 5: Record Your Spending
Use an expense tracker to see how much you actually spend on essential and discretionary categories.
Fundbone guide: How to Track Monthly Expenses in India.
Example: Needs vs Wants on a ₹40,000 Salary
Consider a person earning ₹40,000 per month after salary deductions. Their first priority is to cover essential costs and then decide how much can reasonably go toward lifestyle spending and savings.
| Monthly Expense | Amount | Category |
|---|---|---|
| Rent | ₹10,000 | Need |
| Groceries | ₹5,000 | Need |
| Electricity and mobile | ₹1,500 | Need |
| Work transport | ₹2,500 | Need |
| Essential healthcare | ₹1,000 | Need |
| Restaurant meals | ₹2,000 | Want |
| Entertainment subscriptions | ₹800 | Want |
| Shopping | ₹2,000 | Want |
| Weekend activities | ₹1,200 | Want |
| Total listed spending | ₹26,000 | |
| Income remaining | ₹14,000 |
In this illustration, essential spending totals ₹20,000 and wants total ₹6,000. The remaining ₹14,000 must still be assessed against any unlisted expenses, debt payments, planned savings and other financial commitments.
This example shows why recording all transactions matters. The amount left after a partial list of expenses should not automatically be treated as available savings.
How the 50/30/20 Budget Rule Helps
The 50/30/20 framework provides one way to organise spending into needs, wants and savings or debt repayment.
| Category | Suggested Share | Example on ₹40,000 |
|---|---|---|
| Needs | 50% | ₹20,000 |
| Wants | 30% | ₹12,000 |
| Savings and debt repayment | 20% | ₹8,000 |
These percentages are a starting point, not a requirement. If your rent, medical expenses or family responsibilities are high, adjust the allocation to suit your circumstances.
Read the complete guide: 50/30/20 Budget Rule in India.
How to Reduce Unnecessary Spending
Reducing unnecessary spending does not require removing every enjoyable activity. Focus on purchases that provide limited value or repeatedly push you beyond your budget.
- Set a monthly limit for shopping and dining out.
- Review subscriptions and cancel unused services.
- Compare prices before buying non essential items.
- Wait before making expensive impulse purchases.
- Plan grocery shopping to reduce avoidable waste.
- Avoid buying items simply because they are discounted.
- Review recurring payments every month.
- Transfer planned savings when your income arrives, if practical.
SEBI recommends prioritising basic needs, limiting impulse based purchases when the budget does not permit them, and allocating money regularly toward savings and investments. (SEBI: Management of Income and Expenses)
Common Mistakes to Avoid
- Treating every lifestyle purchase as wasteful: A realistic budget can include planned entertainment and hobbies.
- Ignoring small purchases: Frequent low cost transactions can accumulate into substantial monthly spending.
- Cutting essential healthcare: Do not compromise necessary medical care merely to meet a spending percentage.
- Using credit for wants without a repayment plan: Interest and fees can make discretionary purchases more expensive.
- Setting unrealistic limits: A budget should reflect actual housing costs, family responsibilities and income.
- Forgetting savings goals: Money remaining at the end of the month may be less predictable than a planned savings allocation.
Pros and Cons of Separating Needs and Wants
Pros
- Makes spending priorities easier to understand.
- Helps identify purchases that can be postponed.
- Supports better monthly budgeting.
- Can create more room for savings and debt repayment.
- Helps households discuss spending decisions more constructively.
Limitations
- Some expenses do not fit neatly into one category.
- Essential costs vary by location and household circumstances.
- Cutting discretionary spending alone may not solve a budget shortfall.
- The method does not replace planning for emergencies, debt and long term goals.
Expert View
A practical needs versus wants framework should help you make better financial decisions without making your budget unnecessarily restrictive. Prioritise essential expenses, keep lifestyle spending within an affordable limit and decide in advance how much you want to save.
The RBI and SEBI both provide financial education resources that encourage budgeting, expense management and regular savings. The right allocation will depend on your own financial situation and goals. (RBI financial literacy material, SEBI investor education)
Frequently Asked Questions
1. What is the difference between needs and wants?
Needs are expenses required for essential living, health, safety or important responsibilities. Wants are purchases that improve comfort or enjoyment but can usually be postponed or reduced.
2. Is eating at a restaurant a need or a want?
It depends on the circumstances. Food is a need, but restaurant dining is generally discretionary when an affordable meal can be prepared or obtained another way.
3. Is a mobile phone a need or a want?
A phone may be necessary for work, education, safety or communication. Buying a premium model when a suitable phone already meets your requirements is usually a want.
4. Should savings be treated as a need?
Savings are not a consumption expense, but regular saving should be a priority in your financial plan. Emergency savings can help you manage unexpected expenses without relying entirely on borrowing.
5. How can I reduce wants without affecting my quality of life?
Set a realistic discretionary spending limit and prioritise the activities that provide the most value to you. Reduce purchases that are repetitive, unplanned or less important.
6. How do needs and wants fit into a monthly budget?
List essential expenses first, estimate discretionary spending and then allocate money toward savings and debt repayment. Compare actual spending with the plan each month and adjust it as necessary.
7. Can a want become a need?
Yes, depending on the circumstances. Internet access may be optional for some households but essential for a person who works remotely or studies online.
8. What should I do if my needs use most of my salary?
Review essential costs for reasonable alternatives, check whether any expenses have been incorrectly categorised and avoid unrealistic savings targets. If your essential costs remain high, consider ways to increase income while protecting necessary healthcare and other core needs.
Sources
- RBI: Financial Literacy for School Children, Needs versus Wants
- SEBI: Management of Income and Expenses
- SEBI: Money Matters, Personal Finance Education
- RBI: Financial Awareness Messages
Related Fundbone Guides
- Personal Finance in India: Complete Guide
- How to Create a Monthly Budget in India
- 50/30/20 Budget Rule in India
- How to Track Monthly Expenses
- How Much Should You Save Every Month?
- How to Build an Emergency Fund in India
Disclaimer: This article is for educational purposes only and does not constitute financial, investment, tax or legal advice. Consider your individual circumstances before making financial decisions.

One thought on “Needs vs Wants: How to Manage Your Money in India”